PulseAugur
中
实时 00:00:47
English(EN) Three Eras of Quantitative Finance: How Rule-Based, ML, and Deep Learning Models React to the Same…

深度学习模型在股市分析中表现不如更简单的AI

一项最新研究项目使用10年的苹果公司股票数据,比较了量化金融策略的三个不同时代——基于规则、经典机器学习和深度学习。令人惊讶的是,最复杂的深度学习模型,一种类似于驱动ChatGPT的Transformer架构,在所有指标上的表现最差。一款1990年代的Random Forest模型实现了最佳的风险调整后回报,这表明市场噪音和过拟合会阻碍高度复杂模型在金融应用中的表现。 AI

影响 表明由于市场噪音和过拟合,更简单的AI模型可能比复杂的深度学习架构在金融时间序列分析中更有效。

排序理由 该集群讨论了一个比较不同AI模型类型在金融数据上表现的研究项目,其中包括对一篇已发表论文的引用。[lever_c_demoted from research: ic=1 ai=1.0]

在 Towards AI 阅读 →

AI 生成摘要 · Google Gemini · 来自 1 个来源。 我们如何撰写摘要 →
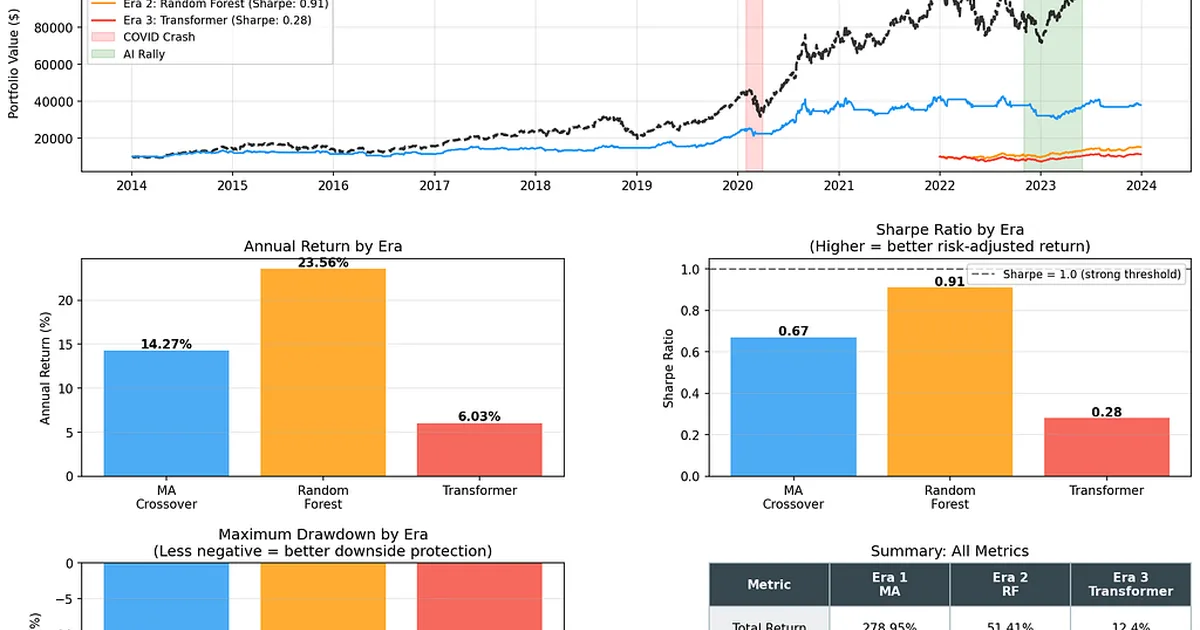
深度学习模型在股市分析中表现不如更简单的AI

本文如何被排名

Signal score
0 / 100
Composite score across the factors below. Higher = stronger signal that this story matters right now.
Newsworthiness bucket
Tool
该集群讨论了一个比较不同AI模型类型在金融数据上表现的研究项目,其中包括对一篇已发表论文的引用。[lever_c_demoted from research: ic=1 ai=1.0]
Source corroboration
Single-source cluster
Only one publisher covered this so far. Single-source stories can still rank when the publisher is high-authority, but they lack cross-source corroboration.
Topics
paper, product
Editorial topic classification. Feeds into how the story surfaces on /topic/<slug> hub pages and into the per-entity coverage mix.
AI-industry relevance
High
Clearly on-topic for AI-industry coverage.
Story freshness
106 days old
Aged out of breaking-news scoring windows; ranking reflects the durable signal from the full source set.

完整方法见我们的编辑标准。

报道来源 [1]

  1. Towards AI TIER_1 English(EN) · ZHU YIXIAO ·

    量化金融的三大时代:基于规则、机器学习和深度学习的模型如何应对相同的…

    <h3>Three Eras of Quantitative Finance: How Rule-Based, ML, and Deep Learning Models React to the Same Market Events</h3><h4><em>A hands-on comparison of strategy behavior and performance across 10 years of real market data</em></h4><p><strong>Introduction</strong></p><p>Quantita…